EPFO’s ₹25,000 wage ceiling: who it covers and what changes on a payslip
Who must join EPF, who can stay outside it, and why a pay rise does not end membership. The old rules explain what the higher ceiling changes.
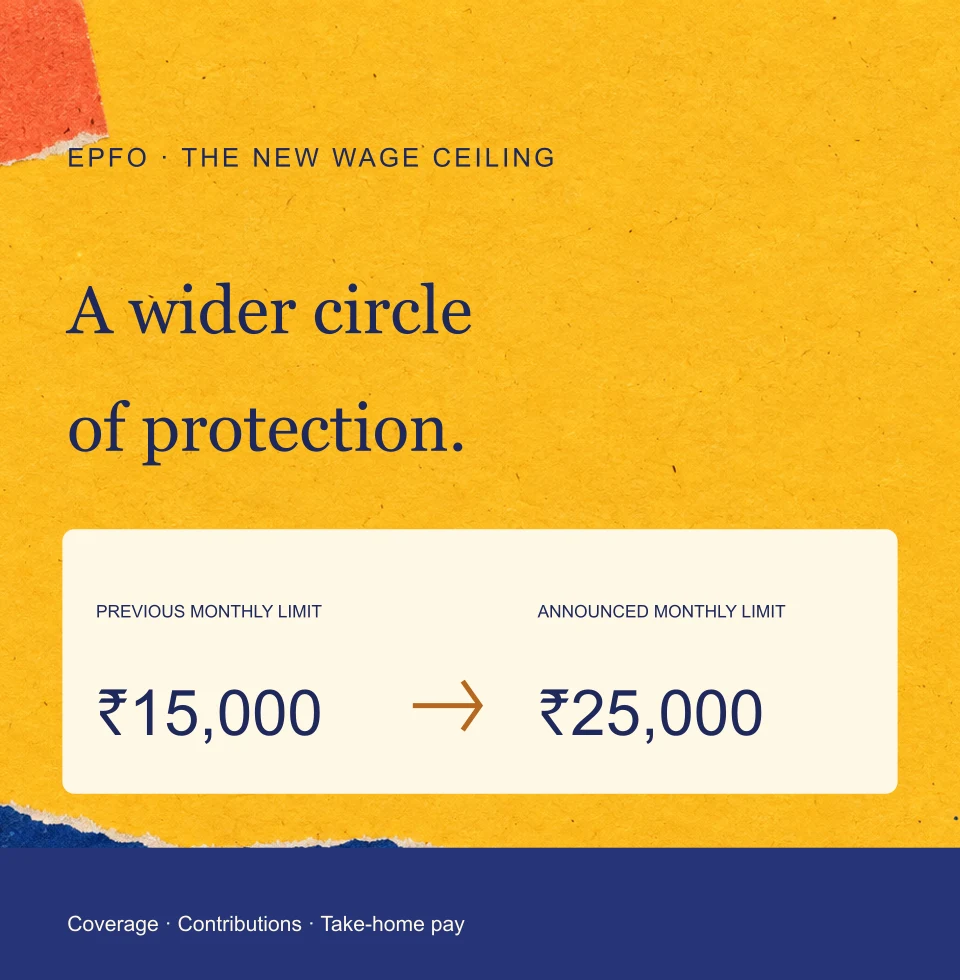
India has raised the wage ceiling for mandatory coverage under the Employees’ Provident Fund Organisation (EPFO) from ₹15,000 to ₹25,000 a month. The Cabinet approved the change on 16 September 2026; the labour ministry announced 17 September as its effective date.
First, how does EPF work?
The Employees’ Provident Fund (EPF) is a savings fund for employees. Each month, the employer deducts the employee’s contribution from their pay and pays a separate employer contribution. The fund builds savings through contributions and interest. EPFO is the organisation that administers it.
Whether EPF is compulsory depends on both the workplace and the employee.
Provident-fund provisions generally apply to establishments with 20 or more employees. Within a covered workplace, an employee’s wages and existing membership determine whether enrolment is compulsory. Here, “wages” means the amount counted under the law, which can differ from total salary or cost to company (CTC).
What was the rule before the increase?
Under the old ₹15,000 ceiling, the ordinary rules for an employee joining a covered workplace were:
- Not already an EPF member, with wages of ₹15,000 or less: the employer had to enrol them.
- Not already an EPF member, with wages above ₹15,000: compulsory enrolment did not apply. They could remain outside EPF, or join voluntarily with their employer’s agreement.
- Already an EPF member: a pay rise above ₹15,000 did not let them stop contributing while continuing in covered employment.
The government’s explanation of the increase describes how fresh employees above the old ceiling were outside automatic coverage. Paragraphs 9 and 10 of the Employees’ Provident Funds Scheme, 2026 distinguish joining the scheme from continuing as a member.
This meant two colleagues earning ₹20,000 could have different obligations. One who had joined EPF when earning ₹12,000 had to continue after a raise to ₹20,000. Another who started at ₹20,000 and had never joined EPF could remain outside it under the old ceiling. Their current salary was the same; their membership history was different.
What does the ₹25,000 ceiling change?
The increase makes enrolment compulsory for employees in covered workplaces whose counted wages are above ₹15,000 and up to ₹25,000, if they were previously excluded because their wages exceeded the old ceiling. Our second ₹20,000 employee now falls within mandatory coverage. The first employee was already a member and continues to be one.
The previous ceiling had stood since September 2014. As wages rose, more people started jobs above the threshold for compulsory membership. Raising the ceiling brings more of those employees into EPF. It does not raise anyone’s salary.
If I earn ₹1 lakh a month, can I stay outside EPF?
Suppose your company has about 50 employees in India and is covered by EPF. Also suppose your wages counted under the scheme exceed ₹25,000; a ₹1 lakh CTC figure alone does not establish that.
If you have never been an EPF member and join above the ceiling, compulsory enrolment does not apply to you. You can remain outside EPF. If you want to join voluntarily, both you and your employer must agree in writing to your enrolment, as paragraph 9(4) allows.
If you are already contributing to EPF, a ₹1 lakh salary does not give you a general right to opt out. A pay rise or a move to another covered employer does not, by itself, end your membership. Voluntarily joining also brings you under the scheme’s continuing membership rules; it is not a monthly choice to turn deductions on or off.
For a member earning ₹1 lakh, the contribution ceiling can limit the wages used to calculate the deduction. The employee contribution is therefore not necessarily ₹12,000 a month; the examples below show how the calculation works.
Monthly wage ceiling · rupees
Common scale: ₹0–₹30,000. Source: Labour Ministry, 16 September 2026.
Which part of your salary counts?
The contribution is calculated on wages defined by law, including basic pay, dearness allowance and retaining allowance, where paid. Some other payments are normally excluded. But if the specified excluded payments exceed 50% of total remuneration, the excess is added back into the wages used for the calculation, as the labour ministry explains. Using only the payslip line labelled “basic pay” can therefore miss part of the wages on which contributions are due.
In the examples above, ₹20,000 means the wages counted after applying those rules. The amount credited to the employee's bank account comes after deductions. Cost to company, or CTC, can also include costs paid by the employer. To calculate the contribution, the employer needs the salary breakdown rather than either of these totals.
How the deduction changes take-home pay
The scheme sets the ordinary employee and employer contribution at 12% of wages, with a 10% rate for categories of establishments specified by the government. Mandatory contributions are capped at the notified wage ceiling; the scheme also permits voluntary contributions above it.
Suppose our ₹20,000 employee joins for the first time and contributes at 12% for a full month. Their employee contribution would be ₹2,400. If their cash wages and other deductions stay unchanged, they would have ₹2,400 less to spend that month, with that amount going into their provident-fund savings.
An existing member may instead see a larger deduction. Suppose their contribution was calculated on the old ₹15,000 limit and their wages are at least ₹25,000. If their contribution base moves to the new limit, the monthly employee contribution rises from ₹1,800 to ₹3,000. With cash wages and other deductions unchanged, take-home pay falls by ₹1,200.
Illustrative monthly employee contribution at 12%
Difference: ₹1,200 per month. Assumes a full month, the 12% rate and a contribution base that moves between these two limits.
For someone already contributing on their full wages above the old ceiling, the increase need not change the employee deduction. The effect depends on the contribution base they were using before the change.
What the employer pays, and what the money provides
The employer must pay its own contribution. Paragraph 21 of the scheme prohibits recovering that contribution from the employee's wages; paragraph 22 allows the employee's share to be deducted. For the newly enrolled employee in our example, the ordinary employer contribution would also be ₹2,400. This is separate from the ₹2,400 deducted from the employee's pay.
The employee's contribution goes into their EPF savings balance, with withdrawals governed by the scheme's rules. For eligible pension members, part of the employer contribution goes instead to the Employees’ Pension Scheme (EPS), which provides pension benefits under its own eligibility rules. This is why the total contributed by the employee and employer may differ from the amount added to the employee's EPF savings balance.
EPFO also administers the Employees’ Deposit Linked Insurance Scheme (EDLI), which provides a benefit to eligible family members or nominees if a member dies while in service.
What to check in the first payslip
The ministry has announced 17 September as the effective date and says statutory and administrative implementation steps will follow. Its release does not spell out how employers should calculate contributions for the wage period containing that date. The first deduction may therefore differ from the full-month examples above.
For an affected employee, the practical checks are whether the employer has enrolled them, which wages and rate it used for the deduction, and whether the payment appears in their contribution records. Compare the two records: the payslip shows what was deducted, while the contribution record shows what reached the fund.